Fintech Technologies: Top 12 Technologies To Consider
TL;DR: The fintech stack that wins in 2026–27 is API-first, real-time, AI-assisted and compliance-ready by design. Start with a secure cloud-native core and one real-time payment or open-data integration, add AI where you have clean data, and treat stablecoins, tokenization and agentic payments as strategic bets rather than day-one requirements. The 12 technologies below are ranked with a build, buy or watch verdict.
Why this list was rewritten for 2026–27
Our 2024 version listed the usual suspects: AI, blockchain, cloud, APIs and biometrics. Since then the ground has moved. India's UPI crossed 24,162 crore transactions in FY26, stablecoin rules moved from drafts to enforcement, and AI agents started to initiate payments on their own. This update keeps what still matters, adds what changed, and tells you how to prioritise. If you are planning a product, our finance app development team can help you scope it.
The 12 technologies at a glance
| # | Technology | 2026–27 maturity | Verdict |
| 1 | Agentic AI | Early production | Pilot with guardrails |
| 2 | Generative AI and LLMs | Mainstream | Build |
| 3 | Real-time payments (UPI and instant rails) | Mature, scaling | Build now |
| 4 | Open banking and open finance | Growing | Build |
| 5 | Embedded finance and BaaS | Growing | Buy plus customise |
| 6 | Blockchain, tokenization and stablecoins | Regulated, selective | Watch, then build for use case |
| 7 | Cloud-native, API-first cores | Mature | Build now |
| 8 | Cybersecurity and zero trust | Mandatory | Build now |
| 9 | Biometrics and deepfake-resistant identity | Mainstream | Buy plus integrate |
| 10 | Big data and predictive analytics | Mature | Build |
| 11 | RegTech and RPA | Mature | Buy plus customise |
| 12 | Mobile-first, super-app and IoT payments | Mature | Build |
1. Agentic AI
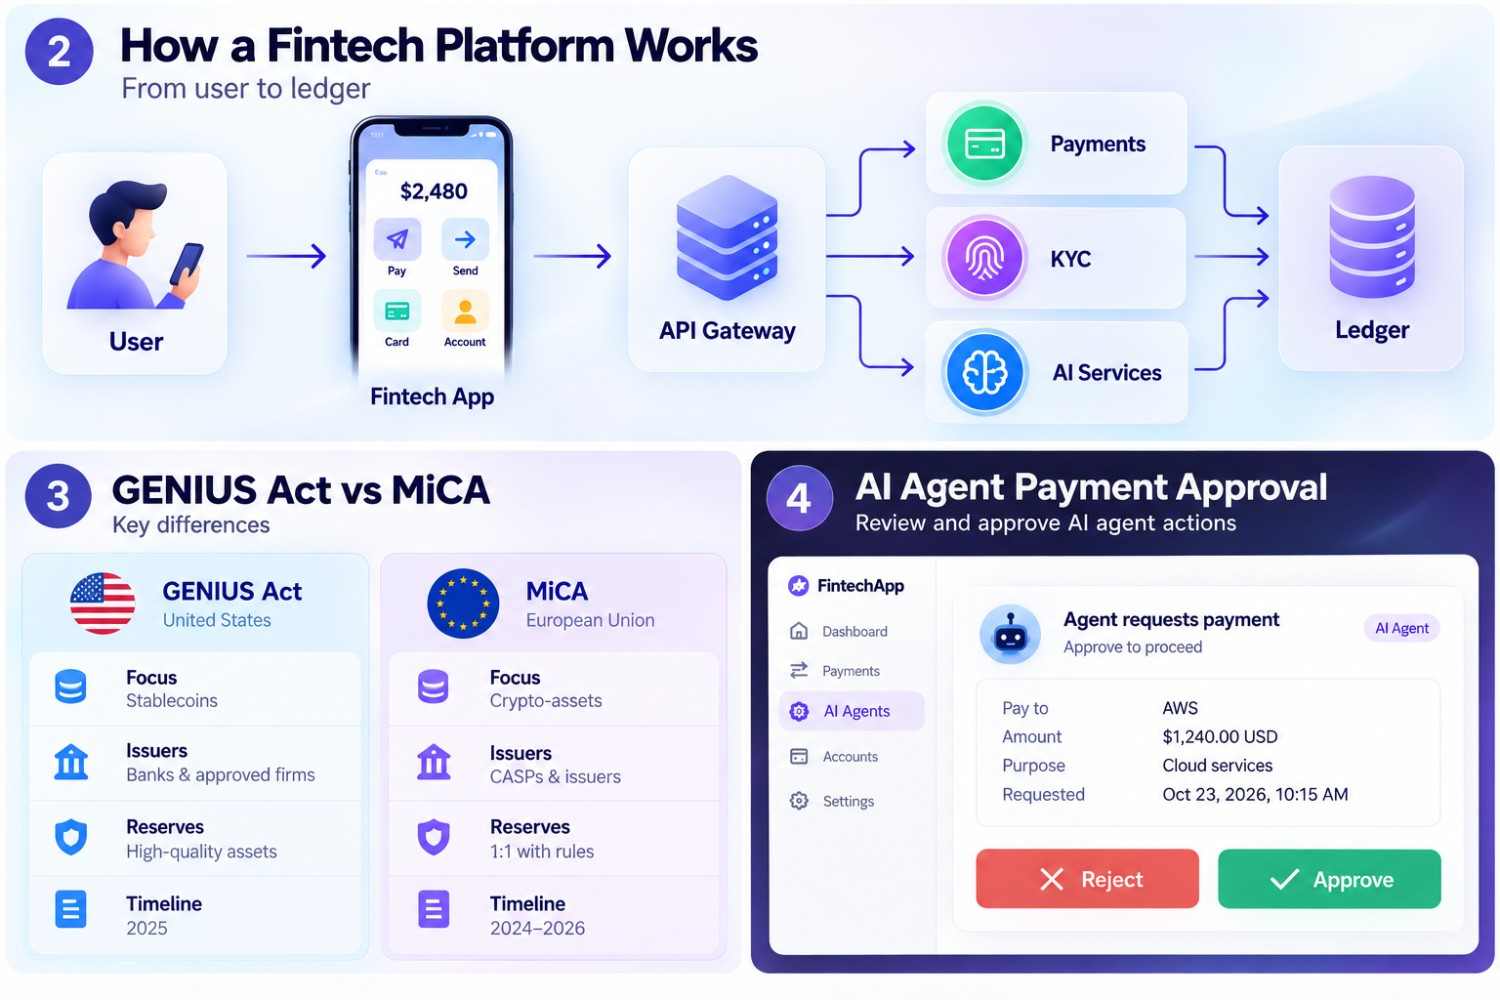
What changed: AI moved from answering questions to completing tasks such as reconciling ledgers, chasing documents, handling disputes and, in early pilots, initiating payments. Infrastructure is emerging for this: Stripe launched its Machine Payments Protocol for AI-agent payments in March 2026.
Best use cases: KYC follow-ups, collections, treasury operations, claims triage.
Build tip: Keep a human approval step for money movement, log every agent action and cap spending limits. See our AI agent development and AI in fintech services.
2. Generative AI and LLMs
What changed: Fintechs use LLMs for support copilots, document summarisation, underwriting notes, compliance drafting and natural-language analytics. The risk is hallucination, so retrieval from approved data and audit trails are now standard.
Build tip: Use LLMs to explain and assist, and keep deterministic rules for credit and compliance decisions. Explore generative AI development and LLM development.
3. Real-time payments: UPI and instant rails
UPI is the clearest proof that real-time rails scale. UPI processed 24.07 billion transactions worth Rs 29.37 lakh crore in September 2026, up 23% year on year, averaging about 802 million transactions a day. A 0.4% merchant discount rate applies from 15 October on specified merchant payments above Rs 2,000, while person-to-person transfers stay free.
Graph: UPI monthly transactions, 2026 (billions) 23.6624.5124.07 Jul 2026Aug 2026Sep 2026Source: NPCI data as reported by StartupTalky and Outlook Money. August was UPI's record month.
Build tip: If you serve Indian users, design for UPI first, including intent flows, mandates and fallbacks, and model the new MDR in your merchant pricing. UPI is also expanding abroad, so cross-border acceptance is a product opportunity. Related: mobile banking app development and digital wallet integration.
4. Open banking and open finance
Consented data sharing (account aggregators, open banking APIs) lets lenders, wealth apps and PFM tools see a user's real financial picture. In 2026–27 the trend is from open banking (accounts) to open finance (insurance, investments, pensions, tax).
Build tip: Treat consent as a product feature: clear purposes, easy revocation and encrypted storage. This powers faster underwriting in loan and lending apps.
5. Embedded finance and Banking-as-a-Service
Payments, lending, insurance and wallets are being embedded inside e-commerce, mobility, SaaS and marketplaces. The winning pattern is to partner with a licensed sponsor bank or BaaS provider and own the user experience.
Build tip: Check partner concentration risk and make sure you can switch providers. Start with one embedded product, such as a wallet or buy-now-pay-later, before adding more. See insurance app development for embedded insurance flows.
6. Blockchain, tokenization and stablecoins
Regulation changed the conversation. The US GENIUS Act, signed in July 2025, created a federal framework for payment stablecoins, and the EU's MiCA is in full enforcement. Issuers face 1:1 reserve rules, AML obligations and a ban on paying interest to holders. Commentary on the rulemaking notes that the real compliance window starts in January 2027, so 2027 is the year builders must be ready.
Best use cases: cross-border settlement, treasury, tokenized assets, programmable payments. Skip it if you have no cross-border or settlement problem to solve.
Build tip: Integrate only with regulated issuers and keep legal review in the loop. Our blockchain development and Web3 development teams can scope this.
7. Cloud-native, API-first cores
Modular, API-first cores let fintechs launch products in weeks and scale on demand. Microservices, event streaming and managed databases are now the default for new platforms; legacy banks are migrating piece by piece rather than in one big bang.
Build tip: Version your APIs, design for idempotency (no double charges on retries) and automate deployment through DevOps services.
8. Cybersecurity and zero trust
Fraud is now AI-assisted, so defence must be too. Core practices: zero-trust access, tokenization of card and account data, real-time transaction monitoring, device intelligence and regular penetration testing. Security teams are also starting to plan for post-quantum cryptography migration.
Build tip: Bake security into the CI/CD pipeline and run red-team tests before launch, not after.
9. Biometrics and deepfake-resistant identity
Face and voice biometrics are everywhere, but deepfakes mean "liveness" is no longer optional. Expect layered identity: document verification, liveness checks, device binding and behavioural signals, with fallback paths for users who cannot use biometrics.
Build tip: Buy proven KYC and liveness providers, then integrate and tune them to your risk model.
10. Big data and predictive analytics
Clean data is the fuel for credit scoring, churn prediction, personalised offers and fraud models. Alternative data (cash-flow, utility, GST and platform behaviour) helps serve thin-file customers when used with consent.
Build tip: Invest in data quality and monitoring first. Models drift, so use MLOps from day one and give leadership a view through Power BI dashboards. Our machine learning team builds these pipelines.
11. RegTech and RPA
Compliance is the most expensive part of fintech growth. RegTech automates KYC/AML, transaction monitoring, regulatory reporting and audit trails, while RPA removes repetitive back-office work. Pair rules with AI for fewer false positives.
Build tip: Buy mature screening tools and build the workflow layer around them so analysts keep full explainability.
12. Mobile-first, super-app and IoT payments
Most users meet your fintech product on a phone. Cross-platform frameworks, passkeys, in-app wallets, wearables and connected devices make payments invisible. Performance and trust (fast load, clear errors, biometric login) decide retention.
Build tip: Ship an MVP on Flutter or native, measure activation and drop-offs, then expand. See also mobile app development and IoT app development.
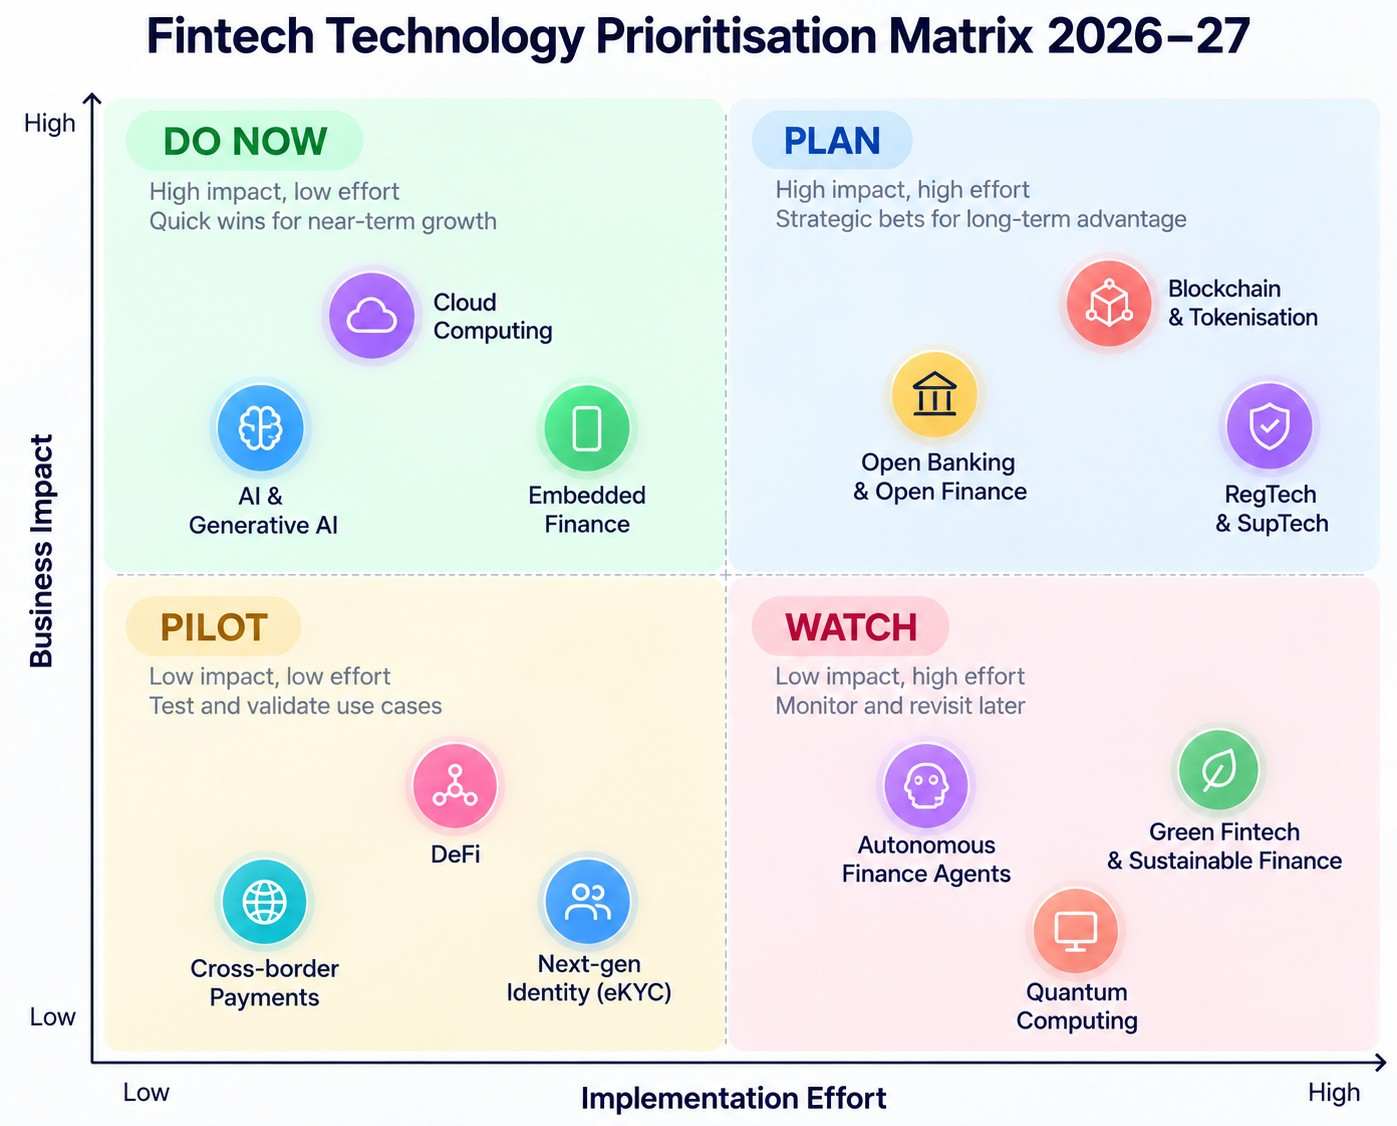
How to choose your stack: a simple 90-day roadmap
| Phase | Focus | Technol0ges |
| Days 1–30 | Foundation | Cloud-native core, API design, security baseline, KYC provider |
| Days 31–60 | Core product | Real-time payment or open-data integration, mobile MVP, analytics events |
| Days 61–90 | Differentiation | AI assistant or fraud model, RegTech automation, pilot of one advanced bet (agentic AI or stablecoin rail) |
Common mistakes to avoid
- Adopting blockchain or AI without a clear problem statement.
- Treating compliance as a post-launch task.
- Letting AI agents move money without limits and human approval.
- Single-vendor dependence for payments, KYC or BaaS.
- Ignoring pricing changes such as UPI MDR when modelling unit economics.
- Skipping security testing before launch.
- Poor data quality feeding credit and fraud models.
- Building every layer in-house instead of buying commodity components.
Fintech technology checklist
- Is the architecture API-first with versioned, documented endpoints?
- Are payments idempotent and reconciled automatically?
- Do you have consent management, encryption and audit logs?
- Is there a liveness-capable KYC flow?
- Do AI features have human oversight, monitoring and fallback?
- Which regulations apply by market (RBI, GDPR, MiCA, GENIUS Act)?
- Who owns maintenance and model monitoring after launch?
Planning a fintech product? Appic Softwares builds payments, lending, trading, insurance and AI-powered finance apps from Jaipur, India and Munich, Germany. Get a free scoping call, explore our case studies, or hire AI engineers. Also see our trading app development and fintech development in Saudi Arabia pages.
Frequently Asked Questions
What are the most important technologies used in fintech?
Key fintech technologies include artificial intelligence, machine learning, blockchain, cloud computing, APIs, big data, cybersecurity, biometrics, IoT, robotic process automation, and mobile technologies.
What are the top 12 fintech technologies to consider in 2026?
The major technologies to consider are AI and ML, blockchain, cloud computing, big data analytics, APIs, cybersecurity, biometrics, IoT, RPA, open banking, digital payments, and mobile technology.
How is AI used in fintech applications?
AI can automate customer support, detect suspicious transactions, assess risk, personalize financial services, analyze data, and assist with financial decision-making.
What role does blockchain play in fintech?
Blockchain provides a distributed way to record and verify transactions. It can support digital assets, smart contracts, secure payments, and transparent transaction records.
Related Articles

Fintech Solutions: 10 Types, Real Examples, 2026 Data and How to Choose or Build One
Fintech solutions have emerged as transformative technologies that are changing traditional financial systems in the fast-developing landscape of the financial industry. The purpose of this blog is to look into the meaning of the term “fintech solutions,” investigate how these solutions are enhancing existing financial systems, and highlight 12 amazing fintech solutions that are altering […]

Expense Tracker App Development- Cost, Monetization, etc 2025
Before the launch of some now-famous expense tracker apps such as Mint, Quickbooks, and more managing expenses was a tedious task. But not now, you can easily manage expenses with the help of these apps and probably save more by tracking where to spend your money and where not. Moreover, the expense-tracking software market is […]

Cost To Create An App Like Zoya Investing In 2025
With the increasing interest in ethical investing, apps like Zoya Investing have become a crucial part of the financial landscape. Zoya Investing, known for its Shariah-compliant investment platform, has gained significant traction among investors. If you’re considering developing a similar app, it’s essential to understand the costs involved in 2024. This article breaks down these […]

15+ Best Tech Stack For Fintech [Code + No Code] In 2025
Have you ever wondered what’s powering those sleek fintech apps you use daily? You know, the ones that let you split bills with friends, invest spare change, or send money across the globe in seconds? Well, buckle up – because we’re about to peek under the hood of modern fintech techstack. Due you know the […]
How AI Agents Are Transforming Financial Markets
Financial markets have continually evolved in response to technological advancements. Electronic trading systems, mobile banking, and other technologies continue to revolutionize how money changes hands. The biggest driver of this change is AI agents in finance. These intelligent systems are no longer just experimental tools being tested by tech companies. They are now the backbone […]
7 Use Cases of Predictive Analytics In Finance
Today, the financial service industry is no longer reliant on simply looking back at previous years of data. Institutions expect that they will be able to not only predict and mitigate risks but also forecast potential market fluctuations and provide personalized customer experiences in real time through predictive analytics. Predictive analytics is an important area […]